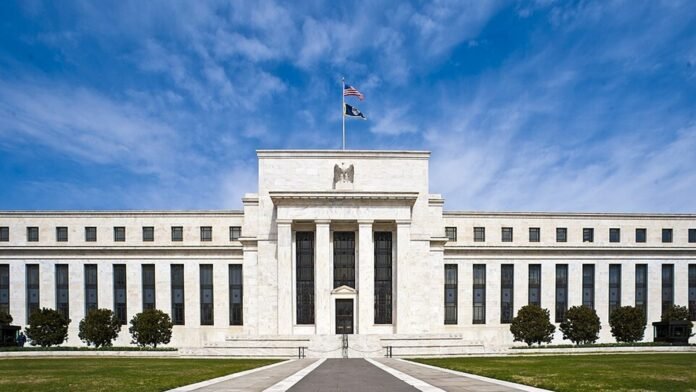
October 29: The US Federal Reserve kept its benchmark target range at 3.75–4% on October 28, with two dissenters arguing for an increase. The decision leaves Asian borrowers and investors watching the persistence of US inflation, rather than receiving a new reduction in dollar borrowing costs.
Key highlights
- The FOMC approved the decision by 10 votes to two.
- Lisa D. Cook and Beth M. Hammack preferred a quarter-point increase.
- The implementation note keeps the reserve-balance rate at 3.90%.
What the committee decided
The Fed’s statement described resilient domestic spending, strong productivity and robust capital investment, while saying inflation remained elevated. It retained its 2% inflation objective and said additional information would help determine the appropriate policy stance.
A hold describes the decision at this meeting. It does not establish that a cut or increase will follow at the next one. The dissent also matters: the disagreement was about whether to tighten policy, rather than whether to begin a fresh round of easing.
The rates at a glance
| Policy instrument | Rate or range |
|---|---|
| Federal funds target | 3.75–4.00% |
| Interest on reserve balances | 3.90% |
| Standing overnight repo | 4.00% |
| Overnight reverse repo offering rate | 3.75% |
The operational settings take effect on October 29, according to the implementation note. These are central-bank instruments, not a schedule of rates that commercial banks must offer households.
How the decision can reach Asian economies
Dollar financing is the most direct channel. A business with a floating-rate dollar loan should check its contract’s reference rate, reset date and margin. An unchanged Fed target does not mean its next interest bill must be identical: contractual reset mechanics and movements in market benchmarks still matter.
Exchange rates provide a second channel. Importers paying in dollars and exporters receiving dollars face different exposures. Their costs also depend on hedging arrangements and local-currency movements, so the same US decision can affect two companies differently.
For Asian central banks, domestic inflation, employment and financial stability remain part of the policy calculation. There is no automatic requirement to match a US decision. Readers should distinguish this transmission mechanism from a claim that a particular Asian market has already risen or fallen because of the announcement.
What to watch
The next useful evidence will be US inflation and employment releases, the committee’s fuller explanation of the debate, and subsequent policy communications. For businesses, the practical task is to map dollar liabilities and payment dates rather than infer a guaranteed exchange-rate direction from the headline.
Our earlier Asian release-time guide covered when the announcement was due; this report covers the decision itself.
Sources
- Federal Reserve: FOMC statement, October 28, 2026
- Federal Reserve: Implementation note, October 28, 2026
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.