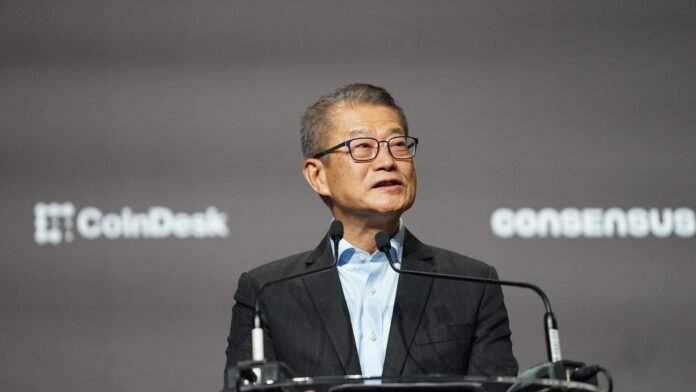
November 9: Hong Kong Financial Secretary Paul Chan urged the accounting profession to prepare for AI-generated evidence and deeper cross-border business activity, saying technological adoption must strengthen rather than replace professional judgment. He addressed the third AFRC Regional Regulatory Forum on Monday.
Key highlights
- Chan highlighted the risk of convincingly fabricated documents.
- He cited uneven AI adoption between large and smaller audit practices.
- Training and evidence assessment were central themes of the speech.
- The remarks did not announce a blanket ban on AI in auditing.
Why the evidence problem matters
Chan’s November 9 speech placed artificial intelligence within a wider discussion of trust in financial reporting. He said auditors need the ability to challenge assumptions and assess evidence as AI makes fabricated material more convincing.
The distinction is between using a tool and accepting its output as proof. A neatly formatted document or a fluent explanation does not establish that a transaction occurred. Equally, an AI-assisted audit process does not become unreliable merely because software was used. The important question is how a conclusion is supported and reviewed.
For investors and businesses reading an audit report, this is a question of assurance quality rather than a promise of absolute certainty. Technology can help examine information, but responsibility for deciding whether the evidence is sufficient remains central to the professional task.
Adoption is moving at different speeds
Chan referred to an AFRC study published the previous month, saying four of five large audit firms surveyed were implementing AI, while adoption among small and medium-sized practices was more uneven. That is the survey comparison he cited, not a finding that four-fifths of every accounting firm in Hong Kong use the same systems.
A firm can also use AI in a limited task without automating its entire audit. The relevant comparison is not simply whether a practice has an AI product, but where it is deployed, what information it handles and how its work is checked.
Smaller practices may face different training and investment constraints. A meaningful assessment therefore needs more than a count of software licences: it needs evidence about skills, governance and the ability to recognise when a tool’s output should be challenged.
Cross-border reporting puts trust under pressure
The finance chief connected the profession’s role with Hong Kong’s international financial activity and the overseas operations of companies seeking capital. He advocated integrity, AI capabilities and training for younger professionals, alongside exchanges and secondments between regulatory counterparts.
For a company operating across several jurisdictions, the financial story may involve different records, teams and commercial arrangements. That creates a practical need for consistent scrutiny across borders. A common technology platform can help organise work, but cannot by itself resolve every difference in underlying information.
The speech presents a policy and professional agenda rather than a new detailed audit standard. Readers should separate the call for stronger judgment from any later binding rule, consultation or inspection requirement issued by the relevant regulator.
At a glance
| Item | Detail |
|---|---|
| Speaker | Paul Chan, Hong Kong Financial Secretary |
| Forum | Third AFRC Regional Regulatory Forum |
| Main AI concern | Credibility of evidence, including fabricated documents |
| Survey figure cited | Four of five large audit firms surveyed implementing AI |
| Professional priorities | Integrity, skills and critical assessment |
What to watch
Future regulatory guidance and training initiatives will show how the concerns become day-to-day practice. For companies appointing auditors, useful questions include how AI-assisted work is reviewed, how source records are validated and how staff escalate conflicting evidence. The speech does not establish that any named company committed misconduct.
Sources
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.