November 10: The Bank of Japan’s newly released Summary of Opinions shows a debate about the pace of further interest-rate increases, rather than a fresh policy change. The document, published on Tuesday, records views from the October 29–30 meeting, when the bank kept its short-term policy rate at around 1.25%.
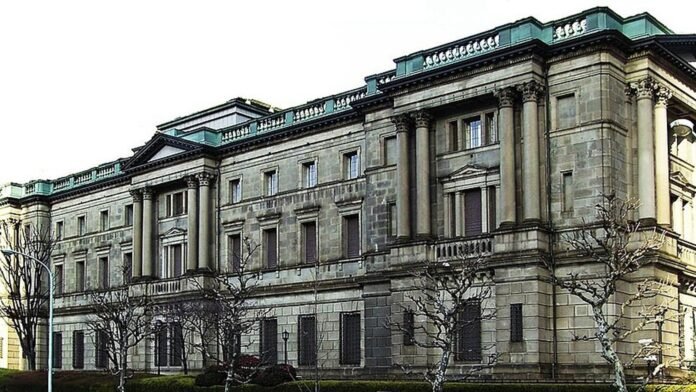
File photo: Bank of Japan headquarters, Tokyo. Ichtrinken / Wikimedia Commons, CC BY-SA 3.0. Cropped and resized. Image source · Licence.
Key highlights
- The November 10 publication summarises an earlier meeting; it does not announce a new rate increase.
- Some opinions supported moving more quickly towards a neutral rate, while others stressed the risk of tightening too far.
- The October decision retained the 1.25% rate by an 8–1 vote.
- Separate September business indicators showed a rising coincident index but a falling leading index.
What the new summary says
The BOJ’s summary describes an economy recovering moderately, with some areas of weakness. Members discussed both demand linked to artificial intelligence and the effects of higher costs associated with the Middle East situation. The document presents underlying consumer-price inflation as broadly consistent with the bank’s 2% objective.
The policy discussion contains different assessments of how much further rates should rise. One opinion favoured a faster approach towards neutrality. Another supported reaching that position while examining developments for several months after each increase. A more cautious view warned that the current rate had already entered the estimated neutral range and that another increase could weigh on activity.
These are individual opinions compiled and edited for publication. The number of bullet points must not be treated as a vote count, and the anonymous views cannot reliably be assigned to named policymakers.
The decision and the publication are different events
The bank’s actual October 30 decision maintained the overnight-rate target at around 1.25%. Board member Hajime Takata proposed 1.5%, but the proposal was rejected. That recorded vote is separate from the anonymous opinions released today.
The same October decision also set out a faster pace for disposing of exchange-traded funds from January 2027: approximately ¥860 billion a year at book value, compared with the existing ¥330 billion pace. Those are balance-sheet transactions, not a change in the overnight interest-rate target. The stated annual pace for Japanese real-estate investment trusts remained unchanged.
Japan’s indicators at a glance
| Measure | Latest official reading | What it describes |
|---|---|---|
| Policy rate, October 30 decision | Around 1.25% | Overnight money-market target |
| September coincident index | 119.5, up 0.7 point | Current business conditions |
| September leading index | 116.4, down 1.6 points | Signals about future conditions |
The Cabinet Office’s November 9 preliminary release retained its assessment of business conditions as improving. Its indexes use 2020 as the base year. They are composite indicators, not percentage changes in GDP.
Why the distinction matters
For borrowers, exporters and investors across Asia, the relevant question is whether incoming evidence supports additional tightening. A discussion of possible increases is not the same as a commitment to a particular date. Likewise, an improving current index alongside a weaker leading index provides a mixed picture rather than a single, definitive growth forecast.
Comparing these releases helps separate three things that can otherwise become confused: a decision already taken, policymakers’ reasoning about future choices, and subsequently published economic data. None of the documents provides a guaranteed path for the yen, lending rates or equity prices.
What to watch
Future inflation, wage and activity releases will help test the competing views. Readers should watch the bank’s next formal policy announcement rather than interpret today’s summary as an unscheduled rate move.
Sources
- Bank of Japan: Summary of Opinions at the October 29–30 meeting
- Bank of Japan: October 30 monetary policy decision
- Cabinet Office: September 2026 indexes of business conditions
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.