October 26: Germany’s Ifo Business Climate Index rose to 90.2 in October from 89.9 in September, according to the institute’s latest release. The improvement was driven by expectations, while companies’ assessment of current conditions weakened slightly. For Asian businesses watching European demand, the distinction is more useful than treating the headline as proof of a broad sales boom.
Key highlights
- The headline needs to be read alongside the sector breakdown.
- An improvement in expectations does not establish stronger completed sales.
- The survey measures sentiment and expectations, not completed export sales.
- Germany’s large goods relationship with China explains one important Asian connection.
What improved and what did not
Ifo reported stronger manufacturing sentiment but a setback in services. Trade was unchanged and construction improved. The breakdown illustrates why one national reading can conceal different business conditions.
As a business survey, the release should be read alongside output and sales data. A respondent’s intention to expand and an expansion that has actually taken place are different stages of the economic story.
The headline in context
| Measure | Result | Interpretation |
|---|---|---|
| September index | 89.9 | Previous monthly reading |
| October index | 90.2 | Improvement in the survey measure |
| Change | +0.3 points | Our calculation: 90.2 minus 89.9 |
| Expectation horizon | Six months | Company outlook, not a growth guarantee |
Our calculation: the difference is 0.3 index points. It should not be described as 0.3% GDP growth, a sales increase or an export forecast.
Why the release matters beyond Germany
Germany’s Federal Statistical Office reported that China was the country’s largest goods trading partner in 2025, with combined exports and imports of €251.8 billion. That annual trade turnover establishes the scale of the relationship; it is not the value of German exports to China alone.
The distinction matters for an Asia-facing reading of today’s survey. German manufacturing can be a customer for components, a supplier of equipment and a competitor in third markets. A positive sentiment reading cannot determine which of those channels will benefit first.
Survey strength is not the same as hard-data strength
In its own October 26 research commentary, Capital Economics said the increase supported its view of a return to growth in the fourth quarter, while noting a discrepancy between stronger surveys and weaker hard data. That is the research firm’s interpretation, not an official growth result.
For exporters, a useful follow-up is to compare the survey with actual enquiries, orders and payment terms in their own sector. A customer’s improved outlook might precede an order, but it may also remain an intention. Keeping those stages separate helps avoid building a sales forecast around one indicator.
What to watch
The next checks are whether order growth becomes production and whether more upbeat expectations spread across sectors. Asian suppliers should look for evidence relevant to their products rather than assume that the national headline applies equally to every German buyer. Today’s release is an improvement in confidence, with an uneven sector picture.
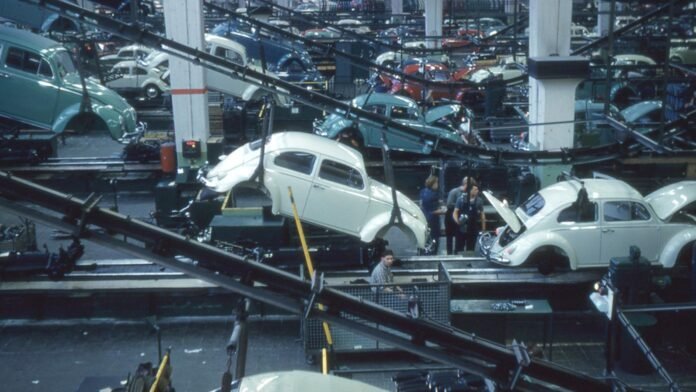
File photo: a Volkswagen assembly line in Wolfsburg in 1960, October 4, 1960. Credit: Roger Wollstadt; CC BY-SA 2.0. Cropped/resized for 1600×900. Historical illustration of German manufacturing, not present-day factory conditions. Image source; Licence. Adaptation shared under the same licence.
Sources
- Ifo Institute: October 2026 business climate results
- Destatis: China was Germany’s largest goods trading partner in 2025
- Capital Economics: Original October Ifo research commentary
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.