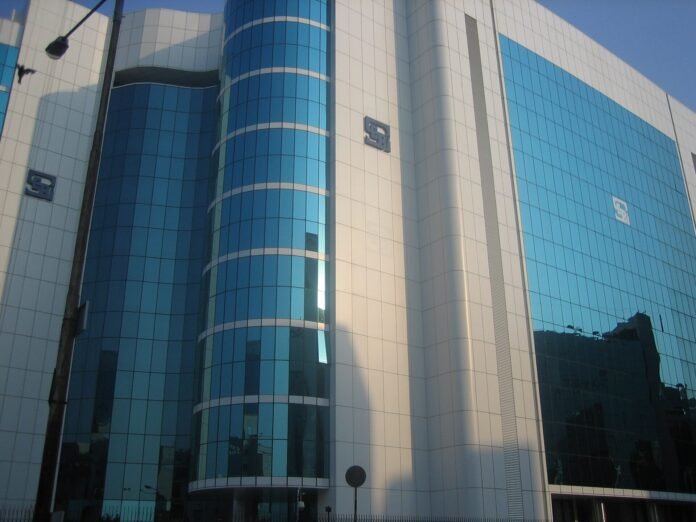
Mumbai, September 27: The Securities and Exchange Board of India (Sebi) has approved one of its broadest rule rewrites of the year. At its board meeting in Mumbai on September 24, the regulator cleared new Portfolio Managers Regulations, a fresh framework for settling enforcement cases, a common advertisement code for market intermediaries and wider access for foreign investors to commodity derivatives, among other changes.
For most retail investors the direct impact is limited, but the decisions change how wealthy clients are served by portfolio managers, how quickly violations can be settled, and what market advertisements can look like.
Key highlights
- New PMS rulebook: The Portfolio Managers Regulations, 2026 replace the 2020 framework; the text shrinks from 70 pages to 33.
- PRIM route: Portfolio managers can invest client money in mutual fund schemes and specialised investment funds (SIFs), with a minimum ticket of Rs 25 lakh and a fee cap of 1% of client assets.
- Wider investment menu: PMS can invest in IPOs, primary debt issues, up to 10% of client assets in investment-grade unlisted debt, and exchange-traded derivatives.
- Settlement overhaul: Formula-based settlement amounts, a notice before the show-cause stage with a 60-day window, and a fast-track route for cases up to Rs 10 lakh.
- Ad code: A common code for regulated entities allows celebrity endorsements at the brand level.
What changes for PMS investors
Portfolio management services serve investors who put in larger sums, and the new rules widen what these managers can buy. According to Outlook Money’s summary of the decisions, portfolio managers can now invest in IPOs and primary debt issues, put up to 10% of client assets into investment-grade unlisted debt securities, take exchange-traded derivative positions up to 1.25 times client assets, and buy foreign securities within the limits of FEMA and the RBI’s Liberalised Remittance Scheme.
The most notable addition is the new PRIM route, under which portfolio managers can place client money into direct plans of mutual funds and SIFs. Sebi’s press release, as reproduced by TaxGuru, sets the minimum ticket at Rs 25 lakh, requires a net worth of Rs 2 crore for new applicants offering this route, and caps the management fee at 1% of client assets. Investment in schemes of an affiliated asset management company is capped at 25%.
Business Standard reported that the board also approved a new category of Independent Fund Managers who can manage portfolios alongside registered portfolio managers. For clients, the practical takeaway is more choice and more flexibility, but also more products to understand: fees, lock-ins and liquidity differ sharply between listed equities, unlisted debt and derivatives.
Lighter compliance for small portfolio managers
Sebi also eased compliance for smaller firms. Portfolio managers with assets under Rs 100 crore, which Outlook Money says make up about 48% of registered PMS providers, get relaxed dealing-room requirements. Graduates can now qualify for the principal officer role, and a standardised investment management agreement is being introduced. The number of provisos in the regulations falls from 47 to 4.
A faster, formula-based settlement system
The second big change concerns settlements, the route through which entities can close enforcement cases by paying an amount without admitting or denying guilt. Under the new Settlement Regulations, 2026, which replace the 2018 framework:
- Settlement amounts will be computed with a formula linked to the minimum prescribed penalties, while wrongful gains will be disgorged separately.
- Sebi can issue a notice before a show-cause notice, giving the entity 60 days to apply for settlement.
- The deadline to apply after a show-cause notice is extended from 60 to 90 days.
- A fast-track route will cover disclosure-related violations where the settlement is up to Rs 10 lakh.
Settlements have also been extended to cases involving misrepresentation of financial statements or diversion of funds, according to Business Standard. The goal is to clear long-running cases faster. The trade-off is that easier settlement must not weaken deterrence in serious fraud cases, which is why the separate disgorgement of wrongful gains matters.
Celebrity endorsements and faster ad approvals
A common advertisement code will now apply to brokers, depository participants, investment advisers, research analysts, online bond platforms, portfolio managers and mutual funds. Celebrity endorsements are permitted for brand-level promotion, and most other advertisements can be issued without prior approval, as long as they are reported within three working days. For investors, the key point remains unchanged: an advertisement is not advice, and return claims should always be checked against scheme documents.
Foreign investors, gold vaults and REITs
- FPIs in commodities: Foreign portfolio investors can trade non-agricultural index derivatives and non-cash-settled non-agricultural commodity derivatives, but must exit before any delivery obligation arises.
- Vault managers: The framework now extends beyond electronic gold receipts, and the net worth requirement rises from Rs 50 crore to Rs 75 crore.
- REITs and InvITs: Depository receipts on units can be listed in IFSC, and approval thresholds move to 75% of votes cast.
- Accredited investors: A new criterion based on securities-market exposure of Rs 5 crore for individuals and Rs 20 crore for corporates and trusts.
What Sebi’s chairman said
Sebi chairman Tuhin Kanta Pandey told reporters that the regulator received more than 3,500 comments on its consultation on the closing auction session. On concerns over merchant discount rates raised by market participants, he said Sebi had heard them and was looking at how to represent them. He also said co-location access in commodity markets must remain fair to all participants.
Why it matters now
The reforms come at a difficult time for Indian equities. The Nifty has fallen for seven straight weeks amid foreign outflows and high oil prices (read our market report). Measures that make products more flexible and enforcement faster will not reverse that trend on their own, but they are part of Sebi’s effort to deepen the market and reduce friction for investors.
Most of the changes will take effect only after Sebi notifies the new regulations and issues detailed circulars, so investors should watch for those before acting.
Sources / References
- Business Standard: Sebi approves PMS-mutual fund route and overhauls settlement rules
- Outlook Money: Sebi board meeting outcome, September 24
- TaxGuru: Sebi Press Release No. 59/2026
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.