NEW DELHI, November 3: A set of GST changes took effect on November 1 that make it easier to give post-sale discounts, speed up refunds for businesses with an inverted duty structure and remove the ₹1,000 floor on refunds for exported goods. The GST Network has also changed the portal’s registration, amendment and cancellation processes, and extended tax deduction at source (TDS) to dealers in used cooking oil, plastic and tyre scrap and e-waste.
Key highlights
- Sections 153 to 155 of the Finance Act, 2026, amending the CGST Act, came into force on November 1 under Notification No. 03/2026-Central Tax dated October 26.
- Post-supply discounts can be excluded from taxable value through a credit note, without a prior agreement, if the buyer reverses the matching input tax credit.
- Businesses with an inverted duty structure can now get 90% of their refund provisionally, as exporters already could.
- The ₹1,000 minimum for refunds no longer applies to tax paid on goods exported out of India.
- Most changes to registration details other than the principal place of business now take effect on submission and online validation.
The law changes
| CGST Act provision | What changed from November 1 |
|---|---|
| Section 15(3)(b) — value of supply | Post-supply discounts can be excluded from value without a pre-agreed arrangement or invoice-by-invoice linkage, if the supplier issues a credit note and the recipient reverses the related input tax credit |
| Section 34(1) — credit notes | Such discounts are now an explicit ground for issuing a credit note; the existing time limit still applies |
| Section 54(6) — provisional refunds | The 90% provisional refund now also covers refunds claimed because of an inverted duty structure |
| Section 54(14) — minimum refund | The ₹1,000 floor does not apply to refunds of tax paid on exported goods; it still applies to other refund types |
The portal changes
| Area | Change announced by GSTN on November 1 |
|---|---|
| New registration (REG-01) | One Person Company added as a separate type of business; supporting documents standardised; new SEZ Entity ID field |
| Amending registration | Changes other than the principal place of business — such as legal name, partners or directors, and additional places of business — take effect on submission and online validation (Notification No. 05/2026-Central Tax) |
| Cancellation (REG-16) | System checks that all returns due up to the cancellation date are filed before approval |
| E-commerce sellers (Rule 14B) | Simplified registration in states where a seller has no physical presence, using an e-commerce operator’s approved warehouse address |
| TDS for scrap dealers | TDS now covers used cooking oil, plastic waste and scrap, tyre waste and scrap, and e-waste, in addition to metal scrap (Notification No. 07/2026-Central Tax) |
| Composition scheme | New category for persons eligible under Section 10(2A), with a facility to change category through REG-14 |
What it means for businesses
Year-end and volume discounts given after a sale have long been a source of disputes over whether tax should be charged on the full or the discounted price. The new rule allows the discount to be adjusted through a credit note without a prior written agreement, but only if the buyer reverses the input tax credit on it — so both sides need to keep their records in step. Faster provisional refunds should help manufacturers whose inputs are taxed at higher rates than their outputs, such as in textiles and fertilisers, by releasing working capital sooner.
Small exporters gain from the removal of the ₹1,000 refund floor on goods exports. Businesses that deal in scrap, used cooking oil or e-waste, and the large buyers who purchase from them, should check whether they now need to register for and deduct TDS.
Our calculation
- Cash flow: on an inverted duty refund claim of ₹10 lakh, 90% — ₹9 lakh — can now be released provisionally while the rest is verified.
- Four new TDS categories: used cooking oil, plastic scrap, tyre scrap and e-waste join metal scrap, which has been covered since October 2024.
What to watch
- CBIC circulars or FAQs on how credit notes for post-sale discounts should be documented.
- The pace of provisional refunds to inverted-duty claimants in the coming months.
- Glitches or delays on the GST portal as the new registration flows bed in.
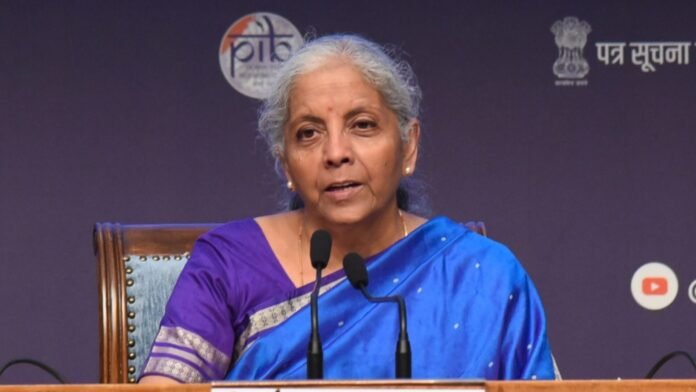
File photo: Finance Minister Nirmala Sitharaman briefs the media after the 56th GST Council meeting in New Delhi, September 3, 2025. Image: Ministry of Finance / Press Information Bureau, Government Open Data Licence – India, via Wikimedia Commons. Photo source · Licence
Sources
- GSTN: Advisory on important changes in FORM GST REG-01
- GSTN: Advisory on simplified registration scheme under Rule 14B
- GSTN: Revised process for approval of cancellation under Form GST REG-16
- GSTN: TDS registration advisory for dealers in scrap and other notified goods
- GSTN: Enhancements related to composition levy functionality
- GSTN: Key changes in the GST registration amendment process
- CBIC: Central tax notifications
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.