October 20: China’s economy expanded 4.5% from a year earlier in the third quarter of 2026, rebounding from 4.3% in the preceding quarter, the National Bureau of Statistics said on October 19. The improvement gives Beijing a stronger starting point for the final quarter, but falling property investment and subdued shopping suggest the recovery remains uneven.
Key highlights
- Third-quarter GDP grew 4.5% year on year, compared with 4.3% in April–June.
- Reuters reported that the result exceeded its economists’ poll forecast of 4.4%.
- September industrial production rose 5.5%, while retail sales increased 1.1%, according to official data.
- Property investment fell 20.6% in January–September; stronger output does not mean the housing downturn is over.
What the latest numbers show
The statistics bureau put growth over the first nine months at 4.6%. It reported a 1.2% quarter-on-quarter expansion in July–September, a different comparison from the headline annual rate. Reuters also reported that the quarterly reading was above its poll’s 1.1% forecast.
Those measures answer different questions. The annual comparison measures output against the same period of 2025; the quarterly comparison tracks movement from the immediately preceding three months. Neither should be described as an annualised growth rate.
At a glance
| Indicator | Latest reading | Comparison period |
|---|---|---|
| GDP | +4.5% | Q3, year on year |
| GDP | +1.2% | Q3, quarter on quarter |
| Industrial production | +5.5% | September, year on year |
| Retail sales | +1.1% | September, year on year |
| Fixed-asset investment | −7.2% | January–September, year on year |
| Property investment | −20.6% | January–September, year on year |
Source: National Bureau of Statistics, cross-checked against Reuters’ October 19 data report. Our calculation: the annual GDP growth rate increased by 0.2 percentage points from the second quarter, not by 0.2%.
Why exports do not tell the whole story
Associated Press reported that robust overseas sales supported the rebound while domestic demand remained weak. AP also reported that Beijing’s annual growth objective is 4.5%–5%. A nine-month result inside that range is encouraging, but it is not a completed full-year outcome.
For an Asian supplier, the composition of demand matters as much as the headline rate. Orders connected to export production can behave differently from orders serving homebuyers or domestic shoppers. A business selling components into a manufacturing chain should therefore not automatically assume that retailers and property developers face the same conditions.
Housing remains a separate test
The official investment series records a contraction in property development spending, rather than a percentage fall in the price of every home. Confusing those measures would exaggerate what the release establishes. It also covers nine months, whereas September’s shopping figure covers one month.
A comparison of those series can show an imbalance, but cannot by itself identify a single cause. Household confidence, borrowing decisions and construction activity operate through different channels. The release should be read as a set of indicators, not as proof that one policy has either solved or caused every weakness.
What to watch
The next question is whether stronger production is followed by broader domestic demand. Subsequent retail, housing and investment releases will help distinguish an export-supported acceleration from a more widely shared recovery. Any additional policy announcement should be assessed separately from these already published figures.
For global readers, the practical takeaway is a modest acceleration with important limits: China is growing, but a higher GDP rate does not establish that all sectors or trading partners benefit equally. This report summarises published data and reporting; it is not a prediction of market returns.
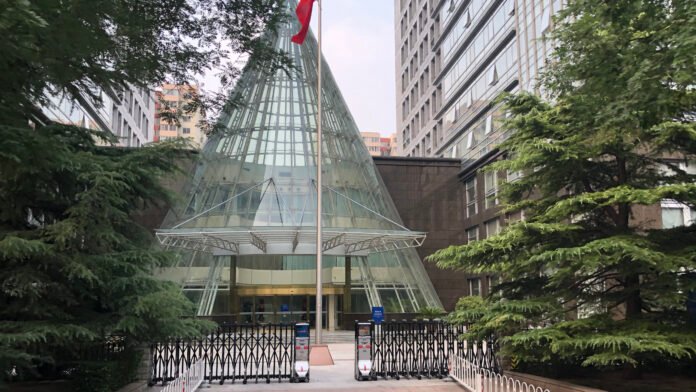
File photo: China’s National Bureau of Statistics in Beijing on September 21, 2020. Credit: N509FZ / Wikimedia Commons, CC BY-SA 4.0.
Sources
- National Bureau of Statistics: National economy in the first three quarters
- Reuters: China’s economic growth accelerates to 4.5% in third quarter
- Associated Press: China’s economy accelerated in the July–September quarter
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.