Explainer | Reviewed on October 17, 2026. India’s Unified Payments Interface has made paying by phone familiar to millions of people. But a large transaction count is not the same as a count of customers, new businesses or additional economic output. Understanding those differences is essential when reading headlines about India’s digital economy.
This guide explains the payment system, its development, the meaning of official statistics and the practical questions that consumers and small businesses should ask. It replaces an unpublished draft built around loosely attributed 2025 growth claims; it is not a report of a newly announced record.
What UPI is—and what it is not
UPI is an instant payment system developed by the National Payments Corporation of India, an RBI-regulated entity. NPCI’s customer FAQs describe it as operating over the Immediate Payment Service infrastructure, allowing transfers between bank accounts at any hour, including outside branch opening times.
The app on a phone and the payment network are different layers. Choosing an app changes the interface through which a customer initiates a payment; UPI is the common infrastructure connecting participating institutions. BHIM is one application using that infrastructure, not another name for every UPI application.
This distinction helps explain why a shop’s payment arrangements cannot be understood simply by looking at the brand displayed on a customer’s screen. The payer, receiving account, participating banks and payment service provider each have a role. For a reader, the important starting question is where the money is going, rather than which app has the most recognisable logo.
How the system developed
NPCI’s official milestones place UPI’s pilot launch in April 2016 and its availability on the Play Store in August that year. Its timeline records BHIM in December 2016, UPI 2.0 in August 2018 and the IPO mandate facility in January 2019.
That chronology matters. UPI was not created as a single response to one subsequent political or economic event. It developed through successive changes in payment infrastructure, interfaces and use cases. A history of its adoption should distinguish the original launch from later features and from the reasons individual customers began using it.
How to read the official transaction numbers
NPCI’s product statistics label transaction volume in millions and value in rupees crore. The August 2026 row available during this review lists 24,508.96 million transactions and a value of ₹29,82,355.95 crore, with 752 banks live on the platform. These are approximately 24.51 billion transactions and ₹29.82 lakh crore in value. This is a dated reference point, not a claim that August is the latest completed reporting month.
The July row lists 23,658.35 million transactions worth ₹29,87,880.49 crore. Comparing those two months illustrates an important point: volume increased while total value was slightly lower. More payments do not automatically mean more money transferred.
Nor does a transaction count identify unique people. One person can make several payments in a day. A comparison also needs consistent periods: a calendar month, financial year and calendar year cannot be used interchangeably. Check the table heading, units and period before accepting a percentage-growth headline.
What the figures cannot establish by themselves
A national payment total does not reveal whether adoption is evenly distributed between towns and villages. It does not measure how confident a first-time user feels or whether someone can obtain help when a payment fails. Those questions require separate evidence rather than an assumption drawn from the aggregate.
Transaction value should not be presented as additional GDP. Transferring money is a payment activity; measuring the production of goods and services is a different exercise. Similarly, a higher digital total does not by itself prove that fraud has fallen or that every household has become financially included. These are analytical limits, not arguments against the usefulness of digital payments.
Why the network can be useful to a small business
NPCI’s UPI product booklet identifies QR-based payments, round-the-clock availability and the ability to accept payments from customers without credit or debit cards among the system’s uses. It also describes the reduction of practical problems associated with exact change and handling cash.
Consider a small shop reconciling its day’s sales. A useful payment system must do more than show a customer a success animation: the merchant needs a dependable record that can be matched to the sale. The relevant business question is therefore not only how many payments were accepted, but how easily exceptions, refunds and disputed amounts can be traced.
That is why merchants should evaluate their own account statements and service arrangements rather than treating a national adoption statistic as a guarantee about their individual experience. This guide does not claim that every product linked to UPI has identical pricing, limits or eligibility conditions.
Safety: receiving money is not authorising a payment
NPCI’s fraud-awareness guidance warns about messages offering rewards in exchange for scanning a QR code and entering a UPI PIN. Those steps are associated with making a payment, not receiving a promised reward. An unexpected request to approve a debit deserves particular caution.
Keep a UPI PIN private. Do not assume that a caller is genuine because they know the name of an app or claim to be resolving a complaint. NPCI also flags unfamiliar app downloads, fake cashback links and online investment schemes among the fraud patterns users should watch for.
If a transaction appears unsuccessful or disputed, use the complaint or transaction-status facility provided through the participating app or bank. Keep the reference number and check the actual account record. Avoid sharing credentials in public comments while trying to obtain assistance.
What a better assessment of UPI should ask
For consumers, useful measures include reliability, understandable payment screens and access to redress. For merchants, they include reconciliation and the handling of exceptions. For public debate, meaningful evidence should distinguish transaction frequency, geographic reach and the number of people actually served.
UPI’s scale is significant, but scale is the beginning of an explanation rather than its conclusion. The strongest account of India’s digital payments combines clearly dated official figures with practical scrutiny of how the system works for the people using it.
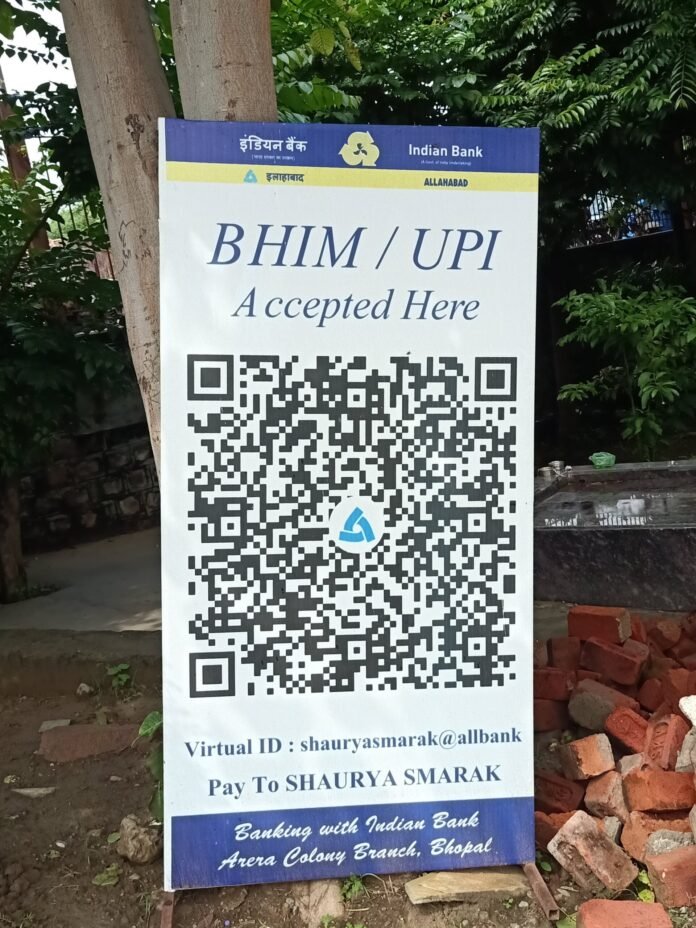
Image credit: File photograph of a BHIM UPI payment sign at Shaurya Smarak, Bhopal, taken on September 5, 2021, by Suyash.dwivedi / Wikimedia Commons, licensed under CC BY-SA 4.0. Resized for display; not a photograph of a new payment launch. The photograph and any adaptations remain under the stated licence.
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.