NEW DELHI, November 4: Growth in China’s services sector slowed to a three-month low in October, Hong Kong’s private sector returned to growth for the first time in three months, and Singapore’s kept expanding at a robust pace, according to purchasing managers’ index (PMI) surveys published on Wednesday by S&P Global and its partners. In all three economies, firms reported rising costs.
Key highlights
- China: the RatingDog China General Services PMI fell to 50.8 in October from 51.6 in September, the slowest growth in three months. The composite output index, which adds manufacturing, eased to 52.0 from 52.4.
- Hong Kong: the S&P Global Hong Kong SAR PMI rose to 50.2 from 49.2, its first reading above 50 in three months. New business from mainland China grew at the fastest pace in eight months.
- Singapore: the S&P Global Singapore PMI eased to 56.7 from 58.1, a five-month low but its 21st straight month above 50. Firms raised purchasing at a record pace.
- Costs: Chinese service firms reported the quickest input cost rise in five months, and Hong Kong firms saw purchase prices rise at a five-month-high rate.
- Mood: Hong Kong business confidence fell to its lowest since August 2020, while Singapore firms’ confidence was the third-highest on record.
| Survey | October 2026 | September 2026 | What it signals |
|---|---|---|---|
| China General Services PMI (RatingDog) | 50.8 | 51.6 | Modest growth, slowest in 3 months |
| China Composite Output Index | 52.0 | 52.4 | Slowest private-sector growth in 3 months |
| Hong Kong SAR PMI | 50.2 | 49.2 | First improvement in 3 months |
| Singapore PMI | 56.7 | 58.1 | Robust growth; 21st month above 50 |
China: growth slows, discounting continues
New business at Chinese service providers kept rising at a solid pace, extending a growth run that began in January 2023, and new export business rose for a sixth straight month, though only marginally. Firms said operational constraints held back activity. Companies hired more staff, on both full- and part-time contracts, and cleared some backlogged work for the first time since October 2025; some cited AI-enabled efficiencies.
Prices moved in opposite directions. Input costs rose at the fastest rate in five months, linked to labour, raw materials and oil, while output charges fell for a second month as firms offered discounts to win sales. Yao Yu, founder of RatingDog, said renewed discounting and rising cost pressures “weighed on profitability”. Business confidence stayed positive but fell to a three-month low.
Hong Kong: back above 50, but firms are worried
Total new orders rose fractionally, ending two months of decline, and new export orders grew for a second month. Firms raised purchasing and input stocks, and suppliers’ delivery times shortened for the first time in six months. But purchase price inflation was among the steepest in five years, and worries about economic conditions and geopolitics pushed business confidence to its lowest since August 2020.
Singapore: demand strong, deliveries slow
Output grew at the softest pace since February 2025, which firms put down to operational constraints, even as new business grew faster than in September and backlogs built up quickly. Companies hired for a fifth straight month, the longest run since 2024. Suppliers’ delivery times lengthened for a fourth month, with firms pointing to international shipping delays, while input cost and selling price inflation eased slightly from September.
Our calculation
- China’s services index fell 0.8 points in a month, while Hong Kong’s rose 1.0 point and Singapore’s fell 1.4 points.
- Singapore stood 6.7 points above the 50.0 no-change line, against 0.8 points for China’s services sector and 0.2 points for Hong Kong.
What it means for India and Asia
China’s service firms are cutting prices even as their costs rise, which squeezes margins and keeps price pressure low in the world’s second-largest economy. Hong Kong’s recovery leans on orders from the mainland. In Singapore, a regional trade and shipping hub, strong demand is running into supply delays. Across all three, higher oil and input costs are a shared theme that also matters for Indian firms that buy from and sell to East and Southeast Asia.
What to watch
- Services PMIs for Japan and other Asian economies over the coming days.
- China’s official October trade and price data.
- Whether Chinese firms keep cutting prices while their costs rise.
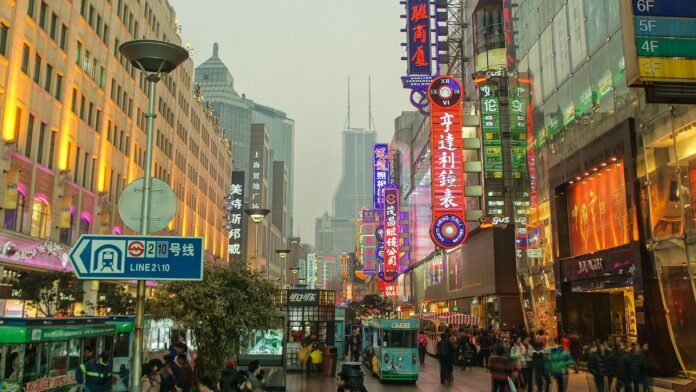
Shoppers on East Nanjing Road in Shanghai. Image: HeroicLife, CC BY 2.0, via Wikimedia Commons. Photo source · Licence
Sources
- S&P Global: RatingDog China General Services PMI, October 2026
- S&P Global: Hong Kong SAR PMI, October 2026
- S&P Global: Singapore PMI, October 2026
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.