October 31: India has constituted a High Level Committee on Banking for Viksit Bharat, giving it six months to recommend reforms to the banking system. The Finance Ministry’s October 30 announcement names former Central Vigilance Commissioner Suresh N. Patel as chairman. Its remit spans regulation, capital requirements, digital innovation and inclusive credit, but the announcement does not itself change banking rules for customers.
Key highlights
- Suresh N. Patel will chair the committee.
- Three named expert members will work with the DFS Joint Secretary for Banking as member secretary.
- The panel has a six-month tenure.
- Its recommendations will cover banking frameworks, capital, AI, cyber safeguards and credit inclusion.
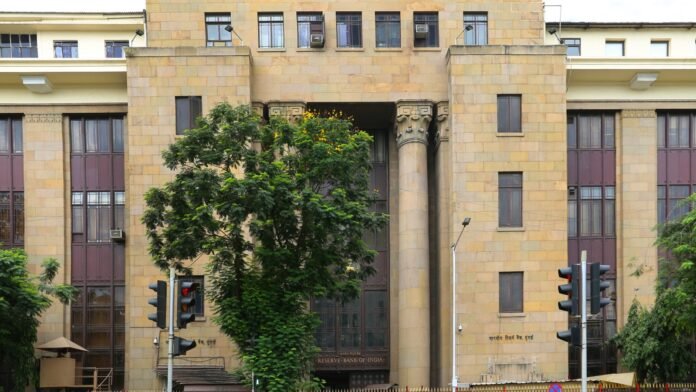
File photo: the Reserve Bank of India building in Mumbai (November 1, 2019). Photo: Sailko / Wikimedia Commons, CC BY 3.0. Cropped and resized; the adapted image retains the stated licence. Not a photograph of the October 2026 event or current conditions.
Who is on the committee
The Finance Ministry names RBI Deputy Governor Shirish Chandra Murmu, former Indian Bank managing director and chief executive Padmaja Chunduru, and former RBI Deputy Governor N. S. Vishwanathan as members. The Joint Secretary for Banking in the Department of Financial Services will serve as member secretary.
The ministry links the committee’s formation to the announcement in the 2026–27 Budget. Its stated purpose is to recommend changes that support a competitive, inclusive and resilient banking system aligned with the Viksit Bharat 2047 goal.
At a glance
| Role | Named person or office |
|---|---|
| Chairman | Suresh N. Patel |
| Member | Shirish Chandra Murmu |
| Member | Padmaja Chunduru |
| Member | N. S. Vishwanathan |
| Member secretary | Joint Secretary (Banking), DFS |
| Tenure | Six months |
What it has been asked to examine
The terms of reference cover banking practices and prudential norms; legal and regulatory frameworks, including those for regional rural and cooperative banks; long-term capital needs; and differences in businesses’ cost of capital. The remit also includes AI and digital innovation with cyber safeguards, workforce capacity, priority-sector lending and the Lead Bank Scheme.
Those topics span several different policy problems. A bank’s ability to obtain capital is not the same question as a borrower’s eligibility for a loan. An institution’s digital investment plan is not the same as a customer-facing rule about using an app. Keeping these questions separate will be important when assessing the eventual recommendations.
The reference to regional rural and cooperative banks also means the exercise is not confined to the largest commercial institutions. However, a broad review does not establish that any particular bank will be merged, privatised or restructured. No such specific outcome is announced in the release cited here.
What changes for customers now
The immediate development is the creation of a review body. It is not a new deposit guarantee, an interest-rate decision, a waiver or a fresh entitlement to credit. Customers should continue to rely on existing bank terms and official regulatory notices for decisions that affect their accounts.
For example, if a future recommendation proposes a different approach to credit delivery, that proposal would still need to be distinguished from an adopted rule. A report may recommend an action without setting its implementation date. Any subsequent legal or regulatory step would need to be assessed on its own published terms.
The AI element raises a similarly practical distinction. Studying a roadmap for digital innovation does not mean that every bank has adopted a common automated lending system. The committee’s explicit reference to cyber safeguards places risk management within the scope of the review, rather than treating technology adoption as an end in itself.
How to judge the next stage
The first milestone will be the committee’s recommendations within its six-month tenure. Useful questions will include which changes require legislation, which fall within existing regulatory powers, how costs are distributed and how the proposals are intended to improve access without weakening resilience.
For businesses, the cost-of-capital review could become relevant to the way financing constraints are discussed. For smaller borrowers, the inclusion-related terms of reference are the more direct point of interest. Neither group should assume a specific benefit before the panel has reported and the authorities have decided what to adopt.
A meaningful follow-up will compare the recommendations with implementation notices, rather than equating the committee’s formation with completed reform. For now, the membership, mandate and six-month tenure are the concrete developments confirmed by the Finance Ministry.
Sources
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.