October 31: Germany’s inflation rate eased to a provisional 2.8% in October, down from 3.3% in September, according to the Federal Statistical Office’s October 30 estimate. The underlying measure excluding food and energy also slowed. The release provides a new price snapshot for Europe’s largest economy, with final October figures scheduled for November 11.
Key highlights
- National consumer-price inflation was provisionally 2.8% year on year.
- The national CPI fell 0.2% from September.
- Core inflation eased to 2.1%.
- The harmonised annual inflation measure was also estimated at 2.8%.
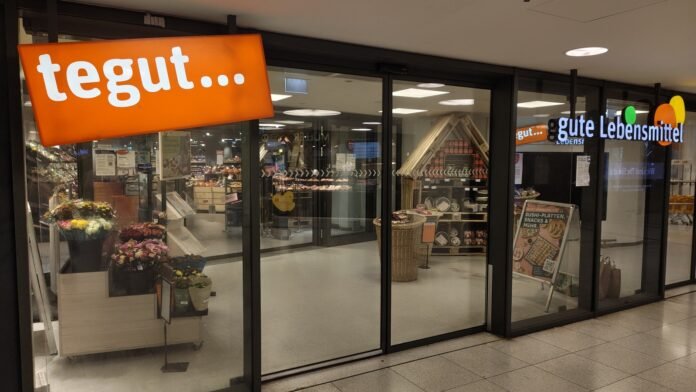
File photo: a supermarket entrance at Munich Central Station in Germany (September 14, 2026). Photo: Cuddly Cuddler / Wikimedia Commons, CC0 1.0. Cropped and resized; the adapted image retains the stated licence. Not a photograph of the October 2026 event or current conditions.
What Destatis reported
Destatis estimated October national CPI inflation at 2.8% annually and minus 0.2% monthly. Its harmonised measure was 2.8% annually and minus 0.1% monthly. The office put core inflation at 2.1%, compared with 2.4% in September.
The provisional category figures show energy inflation at 12.2%, down from 14.9%; services at 2.5%, down from 2.7%; and food at 0.4%, unchanged. Goods inflation was estimated at 3.0%, compared with 3.8% in September. These figures remain subject to the final release.
At a glance
| Measure | October provisional result |
|---|---|
| National CPI, annual | +2.8% |
| National CPI, monthly | −0.2% |
| Harmonised index, annual | +2.8% |
| Harmonised index, monthly | −0.1% |
| Core inflation, annual | +2.1% |
| Final release | November 11, 2026 |
Slower inflation does not mean prices returned to old levels
Our calculation: annual national inflation declined by 0.5 percentage point, from 3.3% to 2.8%. Core inflation fell by 0.3 point. The energy rate declined by 2.7 points, although it remained positive and substantially above the headline figure.
A lower positive annual inflation rate means that the price index is rising more slowly compared with a year earlier. It does not mean the overall price level has fallen back to where it was before earlier increases. The negative monthly national reading answers a different question: the change between September and October.
A simple hypothetical illustrates the distinction. A basket rising from 100 to 103 and then to 105 is still becoming more expensive even though its second increase is smaller. That example explains the arithmetic; it is not a reconstruction of Germany’s published price-index levels.
Why there are two headline measures
The national Consumer Price Index is used for Germany’s domestic price measurement. The Harmonised Index of Consumer Prices is designed for comparisons under the European framework. Their coverage and methods are not identical, so their monthly changes can differ even when their annual rates happen to match.
For a reader comparing Germany with another country, the choice of measure matters. A national CPI figure from one country and a harmonised figure from another may not provide the cleanest comparison. The safest approach is to identify the series explicitly and compare like with like.
Core inflation provides another perspective by excluding food and energy. It does not represent a household shopping bill and should not be described as the rate every family experiences. Households with different consumption patterns can face different pressures even when the aggregate measure slows.
What it means for an Asia-focused reader
The relevant connection is European demand and business planning. An Asian exporter selling to German customers may watch inflation alongside orders, income and financing conditions when assessing the market. This single estimate does not establish that German import demand has risen or that Asian shipments will immediately benefit.
The data also do not constitute an interest-rate decision. A German provisional estimate is one national release; it should not be treated as the same thing as an area-wide inflation figure or a central-bank policy announcement. Claims about an imminent rate move would require separate evidence.
The next firm checkpoint is the final October release, scheduled for November 11. Readers should compare its revisions, if any, with the provisional national and harmonised figures. The October 30 estimate supports a conclusion of slower annual inflation, while leaving the final detail to the subsequent publication.
Sources
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.