October 20: Vietnamese banks are moving to reduce deposit and lending rates following a meeting with the State Bank of Vietnam, as new reporting shows credit growth eased during the first half of October. The measures are aimed at productive businesses and priority sectors, but they should not be read as an automatic reduction in every borrower’s existing loan rate.
Key highlights
- The central bank met commercial banks on October 19 to discuss lower borrowing costs and banking stability.
- Reported instructions include reducing listed deposit rates for maturities of at least six months.
- Several banks have announced targeted lending programmes or rate reductions.
- Credit growth of 11.44% is measured against end-2025, not growth during October alone.
What the central bank is asking banks to do
Viet Nam News reported that Governor Pham Duc An urged lenders to reduce operating costs and share profits to support lower lending rates. Its account of Official Dispatch 9608/NHNN-CSTT says listed deposit rates for terms of six months or longer should fall by at least 0.5 percentage points annually.
The report links the policy to a balance between economic support and financial-system safety. The governor’s message is therefore broader than a headline interest-rate cut: banks are being asked to make room for cheaper credit without encouraging destabilising competition for deposits.
The credit figures, explained
The Investor reported outstanding credit of about VND20,720 trillion as of October 14, equivalent to growth of 11.44% from the end of 2025. It compared that with 11.59% at September’s end. The same report gives October 14 year-on-year credit growth of 16.73%, which uses a different comparison period.
| Measure | Reported figure | Comparison |
|---|---|---|
| Credit growth at end-September | 11.59% | Against end-2025 |
| Credit growth on October 14 | 11.44% | Against end-2025 |
| October 14 annual growth | 16.73% | Against a year earlier |
Our calculation: the year-to-date growth rate eased by 0.15 percentage points between the two reported snapshots. That is not a 0.15% fall in the entire loan stock, nor evidence by itself that every sector is borrowing less.
Different banks, different implementation
VOV’s October 19 account names lenders already responding. It reported deposit-rate reductions at LPBank and VietBank, an ACB plan to lower deposit rates from October 20 and preferential business lending, and Agribank support for production and priority-sector borrowers. It also described a Vietcombank pledge to reduce lending rates by at least two percentage points by year-end.
These announcements have different start dates, customer groups and conditions. A programme’s advertised rate should not be treated as a universal market rate. Borrowers need the bank’s current written offer, including fees, collateral conditions, any introductory period and the rate that applies afterward.
Why a percentage point is not a percent
For a purely illustrative loan, moving an annual rate from 9% to 7% is a two-percentage-point reduction. It is not a reduction to zero, and a two-percent proportional reduction from 9% would be much smaller. This example explains terminology; it is not a quoted offer from a Vietnamese bank.
Similarly, lower deposit rates can reduce future interest income for savers while helping banks reduce funding costs. Whether an existing fixed-term deposit changes depends on its contract. The published policy reports do not establish that banks can rewrite every existing agreement.
What to watch
The next test is implementation: published bank schedules, actual disbursements and subsequent central-bank data. Businesses should distinguish an announced package from an approved loan and ask when any repricing takes effect. This is a news explanation of published reports, not personalised borrowing or investment advice.
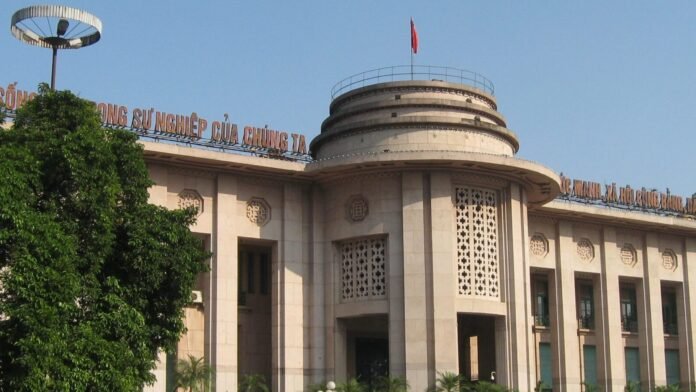
File photo: State Bank of Vietnam headquarters in Hanoi on October 30, 2010. Credit: Daaé, via Wikimedia Commons. Public-domain dedication. Cropped and resized.
Sources
- Viet Nam News: Banks cut costs to lower lending rates for priority sectors
- The Investor: Credit growth slows in the first half of October
- VOV: Governor calls for targeted interest-rate cuts to support businesses
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.