October 30: A new Bank for International Settlements payments report examines how central banks can preserve safe settlement as faster payments, non-bank providers and tokenised arrangements develop. Published on October 29 by the Committee on Payments and Market Infrastructures, it separates the central bank’s monetary and infrastructure responsibilities into four roles.
Key highlights
- The report examines the evolving payment system.
- Central bank money is considered alongside private payment innovation.
- Issuer, operator, overseer and catalyst are distinct roles.
- The report is analysis, rather than a new national payment rule.
Four roles, different decisions
| CPMI role | Question it raises |
|---|---|
| Issuer | Who can access central bank accounts and on what terms? |
| Operator | How should settlement infrastructure develop? |
| Overseer | How should safety and systemic risks be assessed? |
| Catalyst | How can institutions coordinate standards and implementation? |
The report addresses fast payments, non-bank payment-service providers, tokenised deposits and stablecoins. It identifies credit, liquidity, operational and cyber risks as relevant to changing payment arrangements.
The customer screen and the settlement layer
A payment can appear simple to its user: select a recipient, confirm an amount and see a completion message. Behind that interaction, the institutions involved still need a reliable way to settle their obligations to each other.
This is why the speed of a customer-facing application and the safety of the underlying settlement arrangement should be assessed separately. A fast interface does not explain which institution owes money, where settlement takes place or what happens if a participant cannot complete its obligation.
For readers in Asia following expanding digital-payment services, the useful questions are institutional: who holds the funds, who settles with whom and which rules govern the arrangement. The answer can differ across services that look similar on a phone.
Tokenisation changes the record, not the need for clarity
The CPMI analysis treats innovation and confidence in money as related design questions. It considers the contribution of central bank money to reliable settlement and convertibility alongside evolving private arrangements.
A token’s technical format alone does not identify the legal claim it represents. Comparing payment products therefore requires more than asking whether they use a shared ledger or a familiar digital label. The issuer, claim, redemption terms and settlement process remain necessary parts of the description.
Keeping these questions separate also helps avoid equating a tokenised deposit with every stablecoin or with central bank money. Similar technology can carry different institutional responsibilities and different risks.
What coordination would need to achieve
Standards can make systems easier to connect, but agreement on a standard and successful implementation are separate milestones. Participants need to understand responsibilities, operating arrangements and procedures when something goes wrong.
A practical assessment would ask whether an arrangement remains understandable during disruption, rather than judge it only by a smooth demonstration. Access rules, resilience and the handling of participant failure belong in that assessment alongside convenience and speed.
The report supplies a framework for examining those decisions. It does not announce an Indian regulation, require a particular central bank digital currency or change the terms of an individual payment account. Such changes would need their own jurisdiction-specific legal or operating records.
What to watch
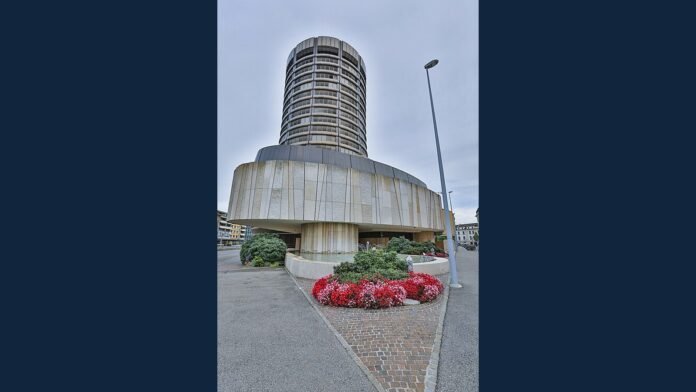
The relevant follow-up will be how central banks and payment authorities apply the analysis in consultation papers, infrastructure decisions and national rules. Those documents should be read in their own jurisdiction and effective-date context. The photograph shows BIS headquarters in Basel in 2012, with its original photographer and licence credited.
Sources
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.