November 2: The European Union’s new €2 Union handling fee applies from November 1 to qualifying distance-sale goods imported into its customs territory. The charge is separate from the temporary €3 customs duty on qualifying low-value consignments. For online sellers in Asia, the crucial detail is that the handling fee is calculated per customs declaration line item, not simply once for every box sent to a European customer.
Key highlights
- The handling fee began on November 1, according to EU and Dutch customs guidance.
- It applies to qualifying distance-sale imports regardless of their value.
- The temporary €3 duty and the €2 handling fee are different charges.
- VAT, tariff treatment and any carrier charges still need to be assessed separately.
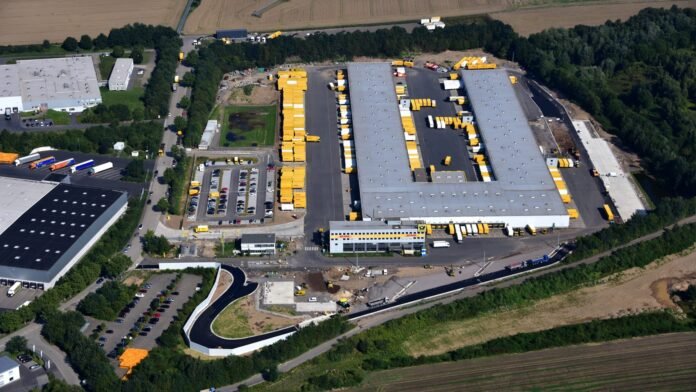
File photo: Deutsche Post DHL parcel centre in Neuwied, Germany (August 29, 2017). Credit: Wolkenkratzer / Wikimedia Commons, CC BY-SA 4.0. Cropped and resized by The Press of Asia; adapted photograph licensed under CC BY-SA 4.0. Archival logistics photograph, not a customs inspection or evidence of a carrier-specific surcharge.
What has changed
The European Commission says the fee helps cover the cost of customs supervision, including checking data, assessing risks and carrying out controls. The Council of the EU confirms the November 1 start and distinguishes the handling fee from the earlier transitional customs duty.
Dutch Customs’ information page, updated on November 2, says the fee is €2 per declaration line for the relevant e-commerce shipments, including those valued above €150. DHL’s operational guidance likewise describes a charge per import customs declaration line item and states that the Union fee is imposed by legislation, rather than being a fee invented by the carrier.
At a glance
| Illustrative declaration | Handling fee only | What is excluded |
|---|---|---|
| One qualifying line item | €2 | VAT, customs duty and carrier charges |
| Three qualifying line items | €6 | VAT, customs duty and carrier charges |
| One line also qualifying for temporary €3 duty | €2 + €3 = €5 before VAT | Other applicable costs |
| Three lines each qualifying for both charges | €6 + €9 = €15 before VAT | Other applicable costs |
Our calculation: the examples multiply €2 by the number of qualifying declaration lines. The combined examples add €3 only where the separate temporary-duty conditions are met. They are illustrations, not a quotation for a particular shipment.
Why an item is not always one physical object
The Commission’s October guidance defines an item by reference to goods sharing the relevant tariff classification, description and, where required, origin. A customs item can therefore group matching goods. Conversely, one parcel can contain several different declaration lines.
This distinction matters when estimating costs from a shopping basket. Counting boxes alone can understate the fee, while counting every physical piece as a different customs item can overstate it. The actual declaration and the applicable classification determine the relevant line structure.
Dutch Customs gives an example of a package with two pairs of trousers, three jumpers and a pair of shoes producing three declaration lines and €6 in handling fees. That official example illustrates the method; it is not a rule that all clothing can always be grouped together regardless of classification or origin.
The €3 customs duty is a separate measure
The temporary €3 duty began on July 1, 2026. The Commission’s detailed guidance sets out the low-value consignment conditions, including the treatment of IOSS and postal consignments. Businesses should use those conditions rather than assume every shipment attracts a flat €5 total.
DHL says both charges may apply to the same qualifying line where the consignment does not exceed €150. For goods above that value, the handling fee can still apply, while the customs-duty calculation follows the relevant tariff treatment. VAT is another component and should not be silently included in an example labelled as the handling fee alone.
What sellers in Asia should review
The immediate operational task is to check the data sent with each order: accurate goods descriptions, values, tariff codes and the information needed to identify the relevant items. Changing an invoice description simply to reduce the number of lines is not a substitute for a correct customs declaration.
Businesses also need clarity about who files the declaration and how the resulting costs are allocated under their selling and shipping arrangements. A charge payable within the customs process and a price displayed to a shopper are related commercial questions, but they are not necessarily the same transaction.
Returns policies deserve attention as well. Dutch Customs says the handling fee cannot be reclaimed merely because delivery fails, a recipient refuses the shipment or the goods are returned. That makes it useful to examine return rates and delivery failures alongside the headline charge when assessing the economics of low-value orders.
A practical review should separate the legal charge from any additional carrier administration fee. If a delivery invoice contains several amounts, ask for the basis of each one rather than treating every amount as the new €2 measure. The photographs of logistics facilities used with this story do not imply that one carrier is responsible for the legislation.
What to watch
The Commission says its guidance will be updated as needed. Importers should monitor the relevant customs authority and their logistics provider for implementation instructions, data requirements and any interaction with national measures. The guidance explains the framework but is not itself the binding legal instrument.
The main change is now in force. Its effect on a particular Asian seller depends on the goods, declaration structure, value, applicable duty and delivery arrangements. Those details are more useful than a blanket claim that every parcel costs exactly €2 or exactly €5 more.
Sources
- European Commission: EU customs reform and handling-fee guidance
- Council of the EU: Action on the influx of small parcels
- Dutch Customs: E-commerce handling fee, updated November 2
- DHL: Union handling fee operational guidance
The Business Desk covers markets, the economy, companies and personal finance. Stories are checked against at least two credible sources before publication.